


Employees dipping into their own pockets to pay expenses. Billing that drags on endlessly. The finance department once again having to chase after everyone just to end up with a handful of crumpled, unreadable receipts. Do these things sound familiar?
All of this speaks in favor of providing employees with a company card instead of relying on reimbursements. But should those cards be prepaid, debit, or credit – and which option is safest, cheapest, and most flexible for your business?
Types of corporate cards
There are three main types of company cards: prepaid, debit, and credit cards. Their main differences come down to their funding source, spend limit, and debt risk.
Comparing prepaid, debit, and credit cards
| Feature | Prepaid | Debit | Credit |
| Funding source | Money is pre-loaded onto the employee’s card. | Draws from the corporate bank account. | Issued by credit provider. |
| Spend limit | The amount pre-loaded onto the card. | The available balance in the bank account. | The approved credit limit. |
| Debt risk | None - cannot spend more than the amount on the card. | Low - depending on whether you have an overdraft. | Medium to high - depending on guardrails on spending. |
Prepaid cards
Prepaid cards work similarly to a petty cash pot, but instead of handing employees cash you can load their prepaid card with the required funds. Where debit cards draw funds from a business bank account, with prepaid cards employees can only spend the amount that has been paid into their card.
Prepaid cards can be used in most scenarios where you would use a debit card, though some limitations may apply - for example, car rental deposits.
Debit cards
The debit card is the most popular means of payment in the private sector. Debit cards require available cash reserves upfront, so if used in isolation they can limit your ability to access additional spending when compared to a credit line.
The key difference between these and credit cards lies in the method of drawing funds: a debit card takes funds directly from the bank account, while a credit card is a way of borrowing money beyond what you actually have, which then needs to be paid back.
Credit cards
Business credit cards allow the user to borrow money and repay in installments. This enables businesses to spread costs over time, helping them to manage cash flow.
Credit cards have more protection from fraud under federal law, with a maximum of $50 liability for unauthorized use if your credit card is stolen. They are also protected under Regulation Z of the Truth In Lending Act (TILA), protecting cardholders when purchased goods or services are not delivered.
However, credit cards carry a higher risk of debt and associated late payment fees than debit or prepaid cards.
Charge cards
Charge cards are similar to credit cards in that they allow you to make credit payments. The main difference is that charge cards require you to pay off your balance at the end of each month.
While these cards don't charge interest, there are usually significant fees associated with them. Their main advantage is that they usually don’t have a spending limit, making them useful for large purchases. Additionally, they can offer high-value benefits and rewards. Due to their high fees, charge cards are typically best suited to senior executives with significant, irregular purchasing needs.
Corporate purchasing cards
P-cards are charge cards specifically designed to be issued broadly across employees, with highly granular controls on spending. They streamline the purchasing process by avoiding the need to raise a PO for each small purchase.
Formats of corporate cards
 Most business card providers offer both physical and virtual cards across prepaid, debit, and credit products. Both options are widely available in digital wallets such as Apple Pay or Google Wallet.
Many modern banks now also offer smart card features, such as customizable spending limits and controls and digital receipt submission.
Integrated solutions, such as Perk Pay, centralize payment and expense data in one place – and offer functionality such as automated categorization and reconciliation of expenses.
Read our guide to how corporate cards can simplify digital transformation to find out how smart cards and integrated solutions can help your business.
Pros and cons of different card types
Key differences at-a-glance
Each type of company card offers different levels of control, flexibility, and risk. Here’s how they compare at a glance:
| Feature | Prepaid | Debit | Credit |
| Cash flow impact | No impact (spend is pre-funded) | Immediate impact on cash reserves | Improves short-term cash flow |
| Risk of employee overspend | None | Dependent on guardrails on spending | Dependent on guardrails on spending |
| Spend controls | Limited | Extensive | Extensive |
| Credit check or personal guarantee required | No | No | Yes |
| Rewards/benefits | Rare | Rare | Extensive |
| Expense tracking and integrations | Limited | Extensive | Extensive |
Fraudulent activity protections
If your card gets stolen, you risk losing money on fraudulent charges. In the US, debit cards are protected from fraudulent activity under federal law. The Federal Trade Commission (FTC) explains that you may be held liable for some of the damages, depending on when you report the card as stolen:
If you report the stolen card before any fraudulent activity occurs, you are not held liable for any damages.
If someone uses the stolen card, but you report it within 2 business days, you will only be held liable for $50.
If you report the stolen card within 60 calendar days after receiving your statement, the maximum you will be held liable for is $500.
Failing to report the stolen card could leave you liable for all related theft damages.
Credit cards have more protection from fraud under federal law, with a maximum of $50 liability for unauthorized use if your credit card is stolen. Many banks now waive this fee, promising a zero liability policy that assures you are not responsible for paying back unauthorized charges.
Purchase protections
Under federal law, purchase protections from disputes such as undelivered goods and services work differently for debit cards and credit cards.
Credit cards are protected under Regulation Z of the Truth In Lending Act (TILA). This protects cardholders when purchased goods or services are not delivered. It does not however protect consumers if the quality of the purchased goods is not up to scratch.
Debit cards are protected under Regulation E, which does not cover undelivered goods.
Many banks offer additional consumer protection policies, including chargebacks in the event of an unresolved dispute with a merchant. These policies can vary across banks and card types, so it’s important to review them before making your choice.
Spend limit and debt risk: Debit card overdraft vs credit card
Some debit cards allow the user to go into an overdraft, meaning it is possible to have a negative account balance up to a pre-approved limit. Typically, fees associated with an overdraft are around $35 per transaction, which can add up to significant amounts if the cardholder is prone to small accidental overspends.
Conversely, credit cards apply a standard yearly interest rate, and therefore are a more stable form of borrowing.
Businesses looking to spend on credit are best off using credit cards for this purpose, and avoid using a debit card overdraft where possible. This means it is important to review your debit card policies for spending guardrails and overdraft protection.
Prepaid cards are best if...
You need tight budget control, with no risk of overspend
You want to enable contractors or temporary staff to make business expenses without the need to reimburse each transaction or keep petty cash
Your business cannot yet access credit (e.g. limited or poor credit history)
Limitations to consider when opting for prepaid corporate cards:
Manual reloads can be time-consuming
Fewer fraud or purchase protections than credit cards
Prepaid cards aren’t as widely accepted as debit and credit cards
Look out for cash withdrawal limits and fees
Debit cards are best if...
You want to access a larger variety of tracking and control features, such as spending limits and category restrictions
You need access to a larger availability of accounting integrations.
You want simple reconciliation of employee spend
You want to avoid borrowing and interest charges
Limitations to consider when opting for corporate debit cards:
Lack of a line of credit, requiring sufficient funds in the associated account
Limited or no rewards or cashback incentives
Potential liability differences depending on provider and card setup.
Potential for limited reporting capabilities
May not offer the same level of purchase protection as credit cards
Credit cards are best if...
You need to manage cash flow by spreading payments over time
Your team regularly makes high-value purchases (e.g. travel, software, ad spend)
You want rewards or cashback on business spending
You need stronger purchase protection (e.g. travel insurance, chargeback rights)
Limitations to consider when opting for corporate credit cards:
Interest charges apply if balances are not paid in full
Higher risk of overspending without strict controls
Personal guarantees may be required for small to medium-sized organizations
Approval processes can be slower than debit or prepaid cards
Annual fees and variable interest rates may apply
How to choose which card type is best for your business needs
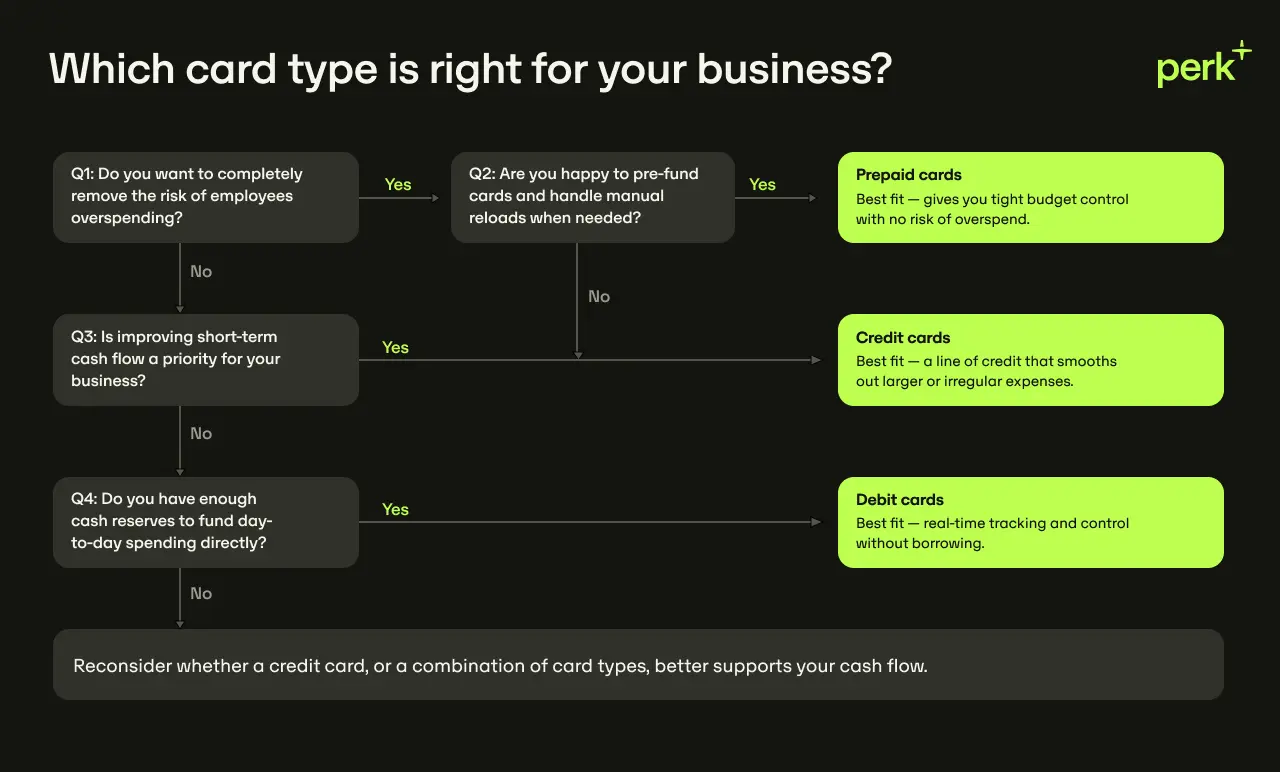
Choosing between prepaid, debit, and credit cards comes down to how you balance control, cash flow, and debt risk. Follow the questions below to see which option is likely to be the best fit for your business.
 Finding the right balance for your company spend
Prepaid, debit, and credit cards each solve different problems, and most teams benefit from a mix. However, juggling multiple card types across different providers can quickly create a mountain of invisible administration.
Finance teams end up wasting hours chasing missing receipts, manually rekeying data, and trying to piece together fragmented spend data at month-end. We call this shadow work: the tedious, manual cycle that pulls your team away from strategic planning and drains business momentum.
Key features of Perk’s spend management platform
All-in-one platform for expenses, invoice processing, and company cards.
Powerful accounting automations.
Book a demo to take control of your spend management with Perk’s powerful, customizable solution designed to bring all your payment methods into a single source of truth.
Written by

Chief Spend Officer, Perk
